
Charitable Giving Strategies for Tax Savings in 2026
 Mahnoor
If you give to charity every year, 2026 is a good time to revisit how you structure those gifts. New federal rules have changed how charitable contributions affect your taxes depending on whether you itemize deductions, take the standard deduction, donate appreciated assets or give directly from an IRA.
The One Big Beautiful Bill Act (OBBBA), signed into law on July 4, 2025, introduced several charitable-giving changes that apply beginning with tax year 2026: a brand-new deduction for people who don’t itemize, a floor that itemizers must clear before any gift counts, and a cap on how much high earners can benefit from itemized deductions at all. None of this changes why you give. It changes what your giving is worth on paper, and with a little planning, you can make sure it’s worth as much as possible.
This guide walks through the charitable giving strategies for tax savings that actually matter in 2026.
Tax Disclaimer: This article provides general educational information about U.S. federal charitable-giving rules for 2026 and is not tax, legal or financial advice. Tax treatment varies based on your individual circumstances, filing status, income, type of contribution and other factors. Consult a qualified tax professional before making charitable decisions based on this information.
What Changed in 2026
Three separate provisions kicked in this year, and it’s worth understanding all three before you decide on a strategy:
- A new deduction for non-itemizers. For the first time since 2021, you can deduct cash gifts even if you take the standard deduction, up to $1,000 for single filers, $2,000 for married couples filing jointly. This deduction only applies to cash gifts to public charities, and it doesn’t apply to gifts made to donor-advised funds or private foundations.
- A 0.5% AGI floor for itemizers. If you itemize, only the portion of your giving above 0.5% of your adjusted gross income counts. On $150,000 of AGI, the first $750 you give isn’t deductible at all, and for most donors, that floored amount doesn’t carry forward to a future year.
- A 35-cent cap for top earners. A new limitation on the tax benefit of itemized deductions for certain high-income taxpayers. For taxpayers affected by the new limitation, itemized deductions, including charitable deductions, can provide an effective tax benefit of no more than 35%, rather than the 37% top marginal rate.
The effect of these changes depends on how you file, how much you give, the type of contribution you make and whether you itemize. That makes the timing and structure of charitable giving particularly important to consider in 2026.
>> Related Post: Key Benefits of Tax-Deductible Donations for Donors in 2026
Charitable Giving Strategies for Tax Savings in 2026:
1. Bunch Multiple Years of Giving Into One
“Bunching” means combining two or three years of planned donations into a single tax year so your total giving clears both the standard deduction and the new 0.5% floor, rather than spreading gifts thin across several years where none of them add up to much of a deduction.
Here’s why the floor makes this more valuable than it used to be: the 0.5% floor is charged once per tax year, not once per gift.
Suppose you have $150,000 of AGI and normally give $9,000 per year. The new 0.5% floor means the first $750 of annual charitable giving doesn’t qualify for an itemized charitable deduction. If your other itemized deductions are not enough to make itemizing worthwhile, spreading $9,000 across three years may also mean you never fully benefit from itemizing. By bunching three years of planned giving $27,000 into one tax year, you may create a larger itemized deduction in that year while taking the standard deduction in another year. The exact benefit depends on your filing status, other deductions and tax situation.
A donor-advised fund (DAF) makes bunching practical: you contribute a lump sum in the high-income year, take the full deduction then, and recommend grants to your favorite causes over the following years at whatever pace suits you.
2. Use Qualified Charitable Distributions (QCDs) if You’re 70½ or Older
If you own a traditional IRA and are at least 70½, a QCD lets you transfer up to $111,000 per person directly from your IRA to a qualified charity in 2026.
A QCD can be a tax-efficient way for eligible retirees to make charitable gifts because a qualifying distribution is generally excluded from taxable income rather than claimed as an itemized charitable deduction. The 0.5% floor doesn’t apply. The 35% cap doesn’t apply. You don’t even need to itemize to benefit. A QCD can also help satisfy your Required Minimum Distribution and keep you below thresholds that affect Medicare premiums and the taxable portion of Social Security.
3. Donate Appreciated Securities Instead of Cash
For qualifying appreciated securities held for more than one year, donating the shares directly to an eligible charity can generally allow an itemizing donor to deduct their fair market value, subject to applicable deduction limits, while avoiding capital-gains tax on the appreciation that would generally arise if the donor sold the shares first. This works whether you’re itemizing or bunching gifts into a DAF, and it’s one of the few strategies in this list that gets more valuable, not less, the longer you’ve held an appreciated asset.
4. Time Your Giving Around the New Non-Itemizer Deduction
If you typically take the standard deduction, don’t overlook the smaller but genuinely new opportunity available to you: up to $1,000 (or $2,000 filing jointly) in cash gifts to public charities is deductible on top of your standard deduction. The catch is that it applies only to cash and unused room doesn’t roll over to next year.
If you are taking the standard deduction in an off year, qualifying cash gifts of up to $1,000 or $2,000 for married couples filing jointly may still provide a federal tax deduction.
5. Consider a Charitable Remainder Trust for Larger Gifts
For donors making substantial gifts of appreciated assets, a Charitable Remainder Trust (CRT) allows you to contribute the asset, receive an income stream for a set period or for life, claim a partial charitable deduction up front, and leave the remainder to charity.
The 2026 federal estate and gift tax basic exclusion amount is $15 million per individual, but estate-planning considerations are highly personal. A CRT may be relevant for donors with substantial appreciated assets who want to combine charitable giving with an income stream and long-term planning. This strategy involves legal and tax complexity, so it’s worth working through with an estate planning attorney or CPA rather than setting up alone.
6. Keep Airtight Records
The new rules make documentation more important than ever, since deductions are lost as often to missing paperwork as to arithmetic. Keep a bank record or written acknowledgment for every cash gift, however small. For any single gift of $250 or more, get a contemporaneous written acknowledgment from the charity before you file, not after. For non-cash gifts over $500, you’ll need Form 8283, and gifts over $5,000 typically require a qualified appraisal. None of the strategies above matter if the deduction doesn’t survive a records check.
>> Related Post: Best Practices for Tax-Deductible Online Giving in 2026
How SAPA Makes Your Giving Go Further
However you structure your 2026 giving, where those dollars land matters just as much as how you claim them. SAPA is a 501(c)(3) nonprofit, tax-exempt since 2019, that puts physicians and healthcare professionals on the ground in Sudan to deliver medical care, nutrition support, and clean water to communities in crisis. In 2025 alone, SAPA’s programs supported over 700,000 patients and screened hundreds of thousands of children for malnutrition.
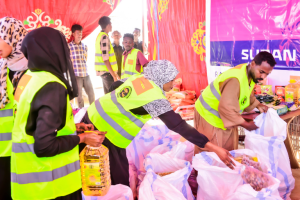
A cash gift to SAPA’s Save a Life in Sudan campaign funds emergency medical response for families caught in active conflict zones. Contributions to the Clean Water program and broader WASH (Water, Sanitation, and Hygiene) initiative fund safe drinking water and sanitation infrastructure that prevents disease outbreaks before they start. And gifts to the Hunger Relief Program put meals directly into the hands of malnourished children and displaced families.
Because SAPA is a qualifying public charity, if your employer offers a corporate matching program, you can also check eligibility and double your donation to SAPA at no extra cost to you.
FAQs
1. What is the biggest charitable giving tax change for 2026?
The most significant change is the introduction of three simultaneous rules under the OBBBA: a new deduction for non-itemizers, a 0.5% AGI floor for itemizers, and a 35% cap on the value of itemized deductions for top earners. Most donors are affected by at least one of these.
2. Can I still deduct charitable donations if I take the standard deduction?
Yes. Starting in 2026, you can deduct up to $1,000 (single) or $2,000 (married filing jointly) in cash donations to a qualifying public charity, even without itemizing. Gifts to donor-advised funds or private foundations don’t qualify for this specific deduction.
3. What is the 0.5% AGI floor and how does it affect me?
If you itemize, the first 0.5% of your adjusted gross income given to charity each year is no longer deductible. On $200,000 of AGI, that’s the first $1,000 of your annual giving. For most donors, this floored amount does not carry forward to future tax years.
4. Is bunching charitable donations still worth it in 2026?
Yes, arguably more than before. Because the 0.5% floor applies once per year rather than once per gift, combining several years of donations into a single year (often through a donor-advised fund) reduces how much total giving gets lost to the floor over time.
5. How much can I donate from my IRA tax-free in 2026?
If you’re 70½ or older, you can transfer up to $111,000 per person directly from your IRA to a qualified charity through a Qualified Charitable Distribution. This amount is excluded from your taxable income entirely and isn’t subject to the new floor or cap.
6. Do donor-advised fund contributions qualify for the new non-itemizer deduction?
No. The new $1,000/$2,000 deduction specifically excludes contributions to donor-advised funds and private foundations. It applies only to direct cash gifts to public charities.
7. Does donating stock still make sense under the new rules?
Yes. Donating appreciated securities directly to charity still lets you deduct the fair market value while avoiding capital gains tax, and this benefit is unaffected by the 2026 floor and cap changes on cash gifts.
8. What records do I need to keep for a charitable tax deduction?
Keep a bank record or receipt for every cash gift, regardless of size. For any gift of $250 or more, obtain a written acknowledgment from the charity before you file your return. Non-cash donations over $500 require IRS Form 8283, and gifts over $5,000 generally need a qualified appraisal.
9. Are the new charitable deduction limits adjusted for inflation?
No. The $1,000/$2,000 non-itemizer deduction is a fixed dollar amount set by statute and does not automatically rise with inflation, unlike some other tax provisions.
10. How can I maximize my tax benefit while supporting SAPA’s programs in 2026?
Consider combining strategies: use a QCD if you’re 70½ or older, bunch larger gifts through a donor-advised fund if you itemize, donate appreciated stock if you hold it, and check whether your employer offers donation matching to double your contribution to SAPA’s clean water and hunger relief programs at no added cost.